
Agri-Tech and Food Production: Claiming Tax Relief on Formulations and Shelf-Life Trials
At a glance
The UK food production and agricultural sectors face continuous pressure to reformulate products, increase shelf-life stability, reduce environmental footprints, and automate processing lines.
Despite the significant technical risks involved in scaling food chemistry and automated farming, many agri-tech and food manufacturing directors fail to realise that their formulation trials and machinery modifications qualify for R&D tax relief.
Qualifying R&D Activity in Food & Beverage Manufacturing
- Clean-Label Reformulation: Removing artificial preservatives or stabilisers while preserving product texture, shelf-life, and microbiological safety.
- Emulsion & Viscosity Stability: Overcoming phase separation in plant-based milk alternatives or low-fat food products under high-temperature pasteurisation.
- Barrier Packaging Innovation: Developing biodegradable or recycled film packaging that maintains protective gas atmospheres to prevent spoilage.
Raw Ingredient Alteration ➔ Thermal / Shearing Stress Testing ➔ Microbiological Analysis ➔ QUALIFYING R&D
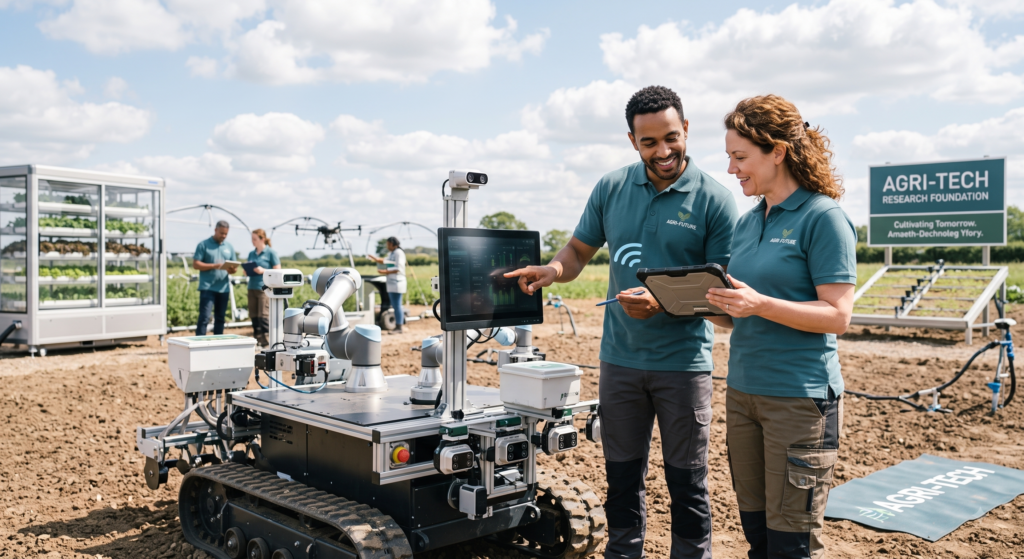
Qualifying R&D Activity in Agriculture & Agri-Tech
- Automated Crop Monitoring Hardware: Engineering custom multispectral camera rigs or sensor arrays to operate reliably under extreme field conditions.
- Precision Dosing Systems: Developing novel fluid control systems for variable-rate fertiliser application to prevent nozzle clogging and inconsistent coverage.
- Vertical Farming Climate Control: Designing micro-climate airflow models to eliminate localised humidity pockets in closed vertical growing units.
Capturing Formulation Consumables
In food processing, trial batches that do not meet quality or safety standards cannot be sold to consumers. The cost of all raw ingredients, packaging films, and utility power consumed during failed or destroyed trial runs qualifies fully as R&D expenditure.
Expenditure Type | Inclusion Criteria |
Raw Ingredients | Food ingredients, enzymes, and active cultures used up during trial runs. |
Laboratory Testing | Third-party lab costs for microbiological, texture, and shelf-life analysis. |
Production Line Staff | Shift supervisor and line technician hours dedicated to test runs. |
Case Study: Plant-Based Dairy Alternative
A speciality food manufacturer attempted to produce a clean-label, oat-based barista milk that would not curdle when introduced to acidic, high-temperature coffee. Standard emulsifiers were excluded by design briefs. Over five months, the processing team conducted 24 trial iterations, altering enzymatic starch conversion temperatures and homogenization pressures.
The raw ingredients, utility costs, and food technician hours totalled £74,000. SeederHeights secured a £11,100 net Corporation Tax credit, offsetting the technical risk of their product development.
Ready to Maximise Your R&D Tax Relief?
Book a free 15-minute review with our specialist team. We’ll assess your technical eligibility and help you claim back your innovation costs—with zero hassle.